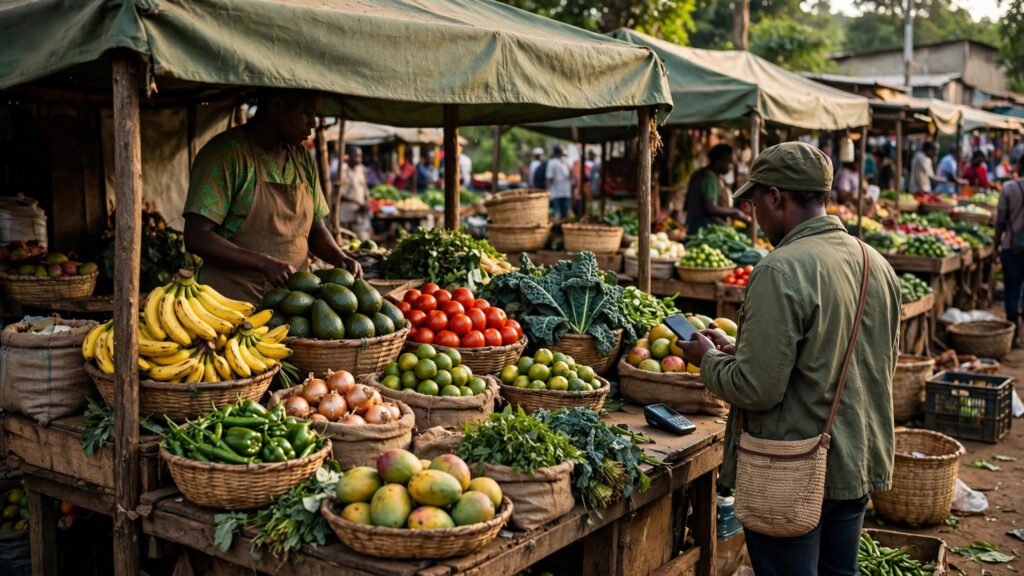
In Kenya, paying with a phone is not a novelty. It is an everyday habit. At a market stall, in a taxi, at a small shop, or when sending help to family in another town, many Kenyans open the same mobile money service and complete the payment in a few taps or menu steps. The service at the centre of that habit is M-Pesa, and its popularity says a lot about how money actually moves in Kenya.
The simple answer is convenience. Cash needs change, a safe place to keep it, and a trip to an ATM or a bank branch. A bank card needs a card machine, and not every small business has one. A phone, by contrast, is already in the buyer’s hand. When the payment method lives on the device people already carry, it removes several small frictions at once.
Key Takeaways
- M-Pesa fits daily life in Kenya because it works on ordinary phones, not only on smartphones.
- It lets people pay, send money, and settle bills without carrying large amounts of cash.
- Its agent network brings money services closer to neighbourhoods, markets, and rural towns.
It Works on the Phone People Already Own
One of the biggest reasons for M-Pesa’s spread is that it does not demand the newest phone. The service can be used through a simple menu on a basic mobile phone, as well as through an app on a smartphone. That matters in a country where many people use affordable handsets and where mobile coverage reaches far beyond bank branches.
For a market trader, a motorcycle rider, or a household helper, that simplicity is the point. There is no need to learn a complicated banking process or to own a card reader. If you can follow a short menu on your phone, you can send or receive money. That low barrier is why mobile money feels less like a banking product and more like a basic phone feature.
If you can follow a short menu on your phone, you can send or receive money.
Cash Is Useful, but Hard to Carry and Keep Safe
Cash still has a place in Kenya, especially for very small purchases. But carrying cash has clear limits. Notes can be lost or stolen, change can run out at a busy stall, and larger amounts are awkward to transport. A phone balance avoids those problems: the money stays in the account until it is sent, and the transaction leaves a record on the phone.
That record matters for both sides of a sale. A buyer can check that a payment went through. A seller can confirm it without counting notes in a crowded market. For small businesses, that confirmation builds trust, and trust is what keeps customers coming back.
The Agent Network Brings Money Closer
Another reason M-Pesa fits Kenya so well is its network of agents. These are small shops and kiosks where people can put cash into their mobile money account or take cash out. Instead of travelling to a distant bank branch, a person can often walk to a nearby agent.
This is especially important outside the big cities. In towns and rural areas, a bank branch may be far away, but a phone signal and an agent are much closer. That closeness turns the phone into a wallet that can be topped up and used near home, which is a practical advantage that a card alone cannot match.
It Fits How Families Support Each Other
Money in Kenya does not only move between buyers and sellers. It also moves between family members. A person working in Nairobi may support parents in a village, help a sibling with school costs, or contribute to a family need at short notice. Sending that help through a phone is faster than posting cash or travelling with it.
That family use is one of the quiet strengths of mobile money. It is not only a checkout tool. It is a way to stay connected financially across distance, and that everyday usefulness keeps people using it long after their first transaction.
- Works on basic phones through a simple menu, as well as on smartphones
- Removes the need to carry large amounts of cash for everyday payments
- Agents let people add or withdraw cash close to home
- Useful for bills, shopping, transport, and family support
Why Not Just a Bank Card?
Bank cards work well in many places, but they depend on a chain of things: a bank account, a card, and a merchant with a working card machine. In Kenya, that chain is not always complete at the point of sale. A roadside stall, a small kiosk, or a rural shop may not accept cards at all, while almost every seller with a phone can accept a mobile money payment.
Mobile money also grew up around a different pattern. In other countries, mobile money has taken a similar path in Ghana, where phone-based payments offer an alternative to cash and cards. In Uganda, too, daily life runs on mobile money for many people who do not rely on a bank account for every payment. Kenya’s story shares that same logic: the phone came first, and the payment system followed the phone.
Bills, Transport, and Everyday Errands
Beyond shopping, M-Pesa is used for the routine payments that fill a week: utility bills, transport fares, airtime, and small services. Paying these from a phone saves a queue and a journey. A bill that can be settled from home, in a minute, is simply easier to keep up with than one that needs a trip across town.
That convenience adds up. When one tool handles shopping, bills, transport, and family transfers, people stop thinking of it as a special payment method. It becomes the default, and defaults are powerful. Cash and cards remain options, but they are no longer the first choice for every transaction.
The pattern is not unique to Kenya. In Ethiopia, Telebirr plays a comparable role for people who prefer phone-based payments over bank cards. Each country has its own service, but the reason people adopt them is similar: the phone is already there, the process is simple, and the money moves when it needs to.
What to Watch Next
Kenyans are likely to keep paying with M-Pesa for the same reasons they started: it works on ordinary phones, it avoids carrying large amounts of cash, agents keep it close to home, and it handles shopping, bills, transport, and family support in one place. Cash and bank cards will still have their uses, but the phone has already become the everyday wallet for many people in Kenya, and that habit looks set to stay.