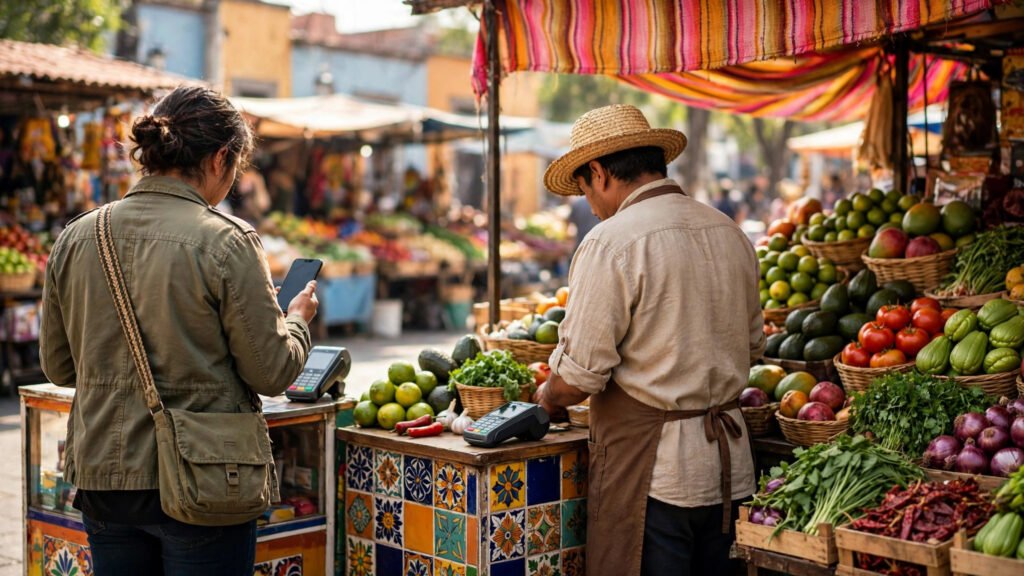
In Mexico, paying someone does not always mean reaching for a card. For rent, a second-hand purchase, a payment to a small business or money sent to family, many people open their bank app and send a transfer instead. Behind most of those transfers is SPEI, Mexico’s interbank electronic payment system.
SPEI stands for Sistema de Pagos Electrónicos Interbancarios. It is operated by Banco de México, the country’s central bank, and it lets money move from an account at one bank to an account at a different bank. The sender does not need the recipient to use the same bank, and the recipient does not need a card terminal. A bank account, a phone and the recipient’s account details are enough.
Key Takeaways
- SPEI is Mexico’s interbank transfer system, operated by Banco de México, and it moves money between accounts at different banks.
- People choose it because it is direct, fast and works bank-to-bank without a card terminal or a shared bank.
- Cards and cash still have a place, but transfers suit larger, planned and person-to-person payments best.
What SPEI actually is
Think of SPEI as the plumbing between Mexican banks. When you send a transfer in your bank app, your bank passes the instruction through SPEI to the recipient’s bank, which credits the recipient’s account. Because the system is shared, it does not matter whether the two people bank with the same institution or with two completely different ones.
To send money, the sender usually needs one of a few identifiers: the recipient’s CLABE, the standard 18-digit account number used in Mexico, a debit card number, or a mobile phone number linked to an account. The exact options depend on the bank app, but the idea is the same — the money travels account to account, not through a card network.
Why transfers beat cards for so many payments
The first reason is reach. Not every seller in Mexico takes cards. A market trader, a freelance worker, a landlord or a small workshop may not have a card terminal, and may not want the cost or paperwork that comes with one. A bank account, on the other hand, is enough to receive a transfer, so SPEI opens up electronic payment to people and businesses that cards never reached.
The second reason is control. A transfer is a deliberate payment: the sender types the amount, checks the recipient and confirms. For rent, school fees, a deposit or a payment to a supplier, that sense of control matters. There is a clear record in both bank apps, which makes it easier to prove a payment was made and to keep track of monthly spending.
The third reason is speed. Transfers through SPEI are designed to settle quickly, often within seconds, rather than waiting for a clearing cycle. For someone selling goods at a market or waiting on a payment before delivering a service, that near-instant confirmation is a practical advantage.
A transfer is a deliberate payment: the sender types the amount, checks the recipient and confirms.
How people use it in everyday life
SPEI transfers show up in all kinds of ordinary situations. Friends split a bill by sending a transfer instead of handing over cash. Families send support to relatives in another city without visiting a branch. Small businesses ask customers to pay by transfer for orders, bookings and services, then check their account to confirm the money arrived before handing anything over.
It also fits how many Mexicans already bank. If the bank app is already on the phone for checking a balance, sending a transfer from the same app is a small step. There is no new app to learn, no new account to open and no separate wallet to top up — the money simply moves from one bank account to another.
- Bank-to-bank: SPEI works across different banks, so sender and recipient do not need the same institution.
- No terminal needed: sellers can be paid without card machines or extra hardware.
- Clear record: both sides keep a bank statement entry showing the payment.
- Phone-first: most transfers are started and confirmed inside a regular bank app.
Where cards and cash still win
None of this means cards have disappeared. For a quick purchase in a supermarket or a large store, tapping a card is still faster than opening an app, typing details and confirming a transfer. Cards also carry protections and instalment options that a plain transfer does not offer, which matters for bigger retail purchases.
Cash, too, remains part of daily life in Mexico, especially for small purchases, tips and places where connectivity is weak. A transfer needs a charged phone and a data or internet connection, and in areas with patchy coverage that is not always guaranteed. The sensible picture is not one payment method replacing the others, but each one fitting the situation it suits best.
How Mexico compares with its neighbours
Mexico is not alone in moving towards instant bank transfers. In Brazil, Pix has changed how Brazilians pay by making instant transfers the default for everyday payments. In Colombia, wallets such as Nequi and Daviplata play a similar role, and in Peru Yape and Plin have made phone-to-phone payments common. The pattern across Latin America is the same: people want money to move directly, quickly and without depending on a card.
What makes Mexico’s version distinctive is that SPEI sits underneath the banks themselves. It is infrastructure rather than a single consumer brand, so the experience can look slightly different in each bank app while the underlying transfer works the same way.
What to Watch Next
SPEI already fits the payments Mexicans make most often between people and small businesses, and its bank-to-bank reach and quick settlement are the reasons it keeps growing as a habit. Cards will keep their edge for fast retail purchases and cash will remain useful where connectivity is weak, but for planned, person-to-person and business payments, the transfer has become the natural default. The next thing to watch is how smoothly transfers work alongside newer options such as QR-based payments, and whether everyday shopping follows the same direct, account-to-account path that transfers have already made normal.