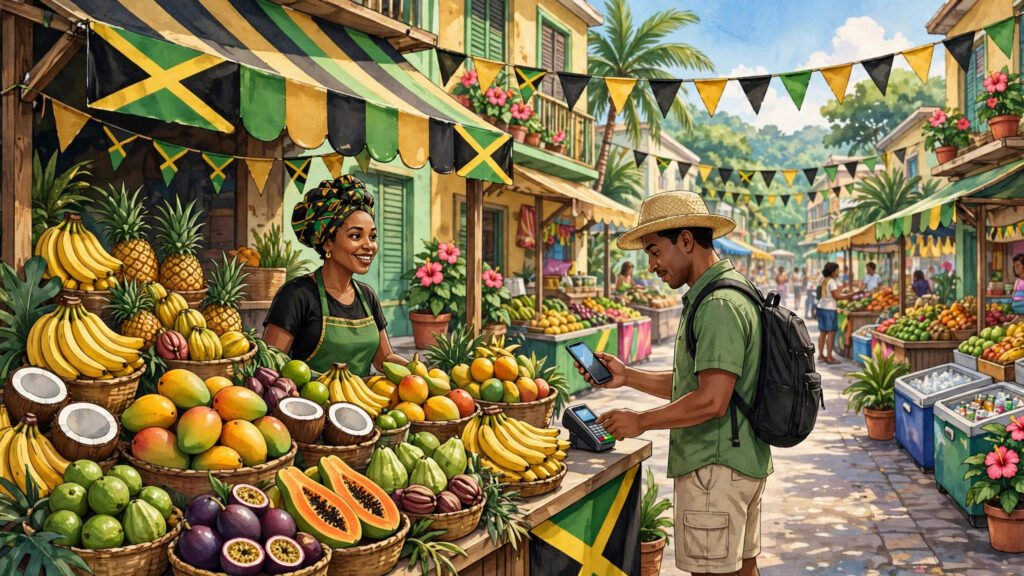
Cash has long been king in Jamaica, from the market stalls of Kingston to the small shops that line roads across the island. Yet in recent years, the country’s central bank has been pushing a very different idea: a digital version of the Jamaican dollar, issued by the Bank of Jamaica itself, that people can hold and spend from a phone. It is called JAM-DEX, and understanding why Jamaica built it explains a lot about how small island economies are thinking about money in the digital age.
So why did Jamaica build its own digital currency? The short answer is inclusion. A central bank digital currency is not a private cryptocurrency and it is not a bank app. It is money issued directly by the central bank, in digital form, designed to work alongside banknotes and coins. For Jamaica, the goal was to give more people a safe, simple way to pay and receive money digitally, including people who do not use a traditional bank account for everything.
Key Takeaways
- JAM-DEX is a digital version of the Jamaican dollar, issued by the Bank of Jamaica itself.
- The aim is wider financial inclusion and cheaper, simpler digital payments across the island.
- Cash is not disappearing: JAM-DEX is designed to work alongside banknotes and coins, not replace them overnight.
What JAM-DEX actually is
Think of JAM-DEX as the Jamaican dollar in digital form. One unit of JAM-DEX is meant to hold the same value as one Jamaican dollar in cash, because both are issued by the same central bank. That is the key difference from cryptocurrencies, whose value can swing sharply and which are not issued by any central bank.
In practice, people access JAM-DEX through a digital wallet on a phone. They can load it, send it to another person, and pay a participating merchant, much like sending money through a mobile wallet. The experience is meant to feel familiar: tap, confirm, and the payment is done. For people who already pay for things with their phones, the step is a small one. For people who mainly use cash, the wallet is a new option rather than a forced replacement.
JAM-DEX is designed to work alongside banknotes and coins, not replace them overnight.
Why Jamaica moved first in the Caribbean
Jamaica was among the first countries in the world to launch a central bank digital currency, and the first in its region to take the step. That timing was not an accident. The island has a large informal economy, many small businesses, and communities spread across parishes where a bank branch may not be nearby. Moving money in cash costs time and effort: cash must be transported, stored securely, and counted, and those costs fall on shops, banks, and customers alike.
A digital currency offered a way to cut some of that friction. A market vendor who accepts a digital payment does not need to carry large amounts of cash home at the end of the day. A customer who receives money digitally does not need to travel to collect it in person. And a small business can keep a clearer record of what came in and what went out. None of this removes the need for cash entirely, but it gives people a practical alternative where cash is awkward or costly.
There is also a broader Caribbean context. Island economies depend heavily on tourism, remittances from family members abroad, and trade across water. Phones already play a central role in daily life across the region, from booking trips to staying in touch with family overseas. Readers curious about how neighbouring islands use their phones day to day can see how Saint Lucians use phones for tourism and work, a reminder that the phone has become the pocket office, shopfront, and travel desk for many Caribbean people at once.
Financial inclusion, in plain terms
Financial inclusion sounds technical, but it describes something simple: whether ordinary people can use affordable financial services. A person who can receive pay digitally, save a little, and send money to family without a long journey or a high fee is more included than a person who can only deal in cash. Jamaica’s push for JAM-DEX sits squarely in that idea.
For unbanked and underbanked Jamaicans, a central-bank wallet can be a first step into digital finance without the paperwork and minimum balances that sometimes come with a traditional account. For small merchants, accepting digital payments can mean serving customers who prefer not to carry cash. And for the wider economy, more digital payments can mean more transactions that are recorded, which helps businesses plan, borrow, and grow.
- JAM-DEX is central bank money in digital form, not a private cryptocurrency.
- It is accessed through a phone wallet and used for everyday payments and transfers.
- Its purpose is inclusion: reaching people and small businesses that cash serves awkwardly.
- Cash remains part of the system, so nobody is forced to switch at once.
How it compares with mobile money elsewhere
Jamaica’s experiment is part of a worldwide shift, but it is not the same as the mobile money systems that grew up in other countries. In much of Africa, for example, mobile money took off through telecom companies, with people storing value on a phone account run by a mobile operator. Readers can compare that model in how Ghanaians pay with mobile money instead of bank cards and how Haitians pay with MonCash instead of bank cards, where operator-led wallets became everyday payment tools.
JAM-DEX differs because the issuer is the central bank itself. That gives it the same backing as a banknote, and it means the digital dollar is a direct liability of the Bank of Jamaica rather than a balance held with a private company. The trade-off is that adoption depends on wallets, merchants, and public trust all moving together: a digital currency is only useful where people can actually spend it, so banks, payment providers, and shops all have a role in making it work.
The challenges Jamaica still faces
Building a digital currency is easier than getting everyone to use one. Habits change slowly, and cash has real advantages: it works without a signal, without a charged phone, and without learning a new app. In rural parishes and during storms or power cuts, those advantages matter. Trust matters too. People need to believe the wallet is safe, that a payment will arrive, and that help is available if something goes wrong.
There is also the question of reach. A digital currency helps most when merchants accept it widely, when wallets are easy to set up, and when the system works on the kinds of phones people actually own. Jamaica’s rollout has therefore been as much about education, merchant sign-up, and practical support as it has been about the technology itself. Other countries watching Jamaica will be looking less at the launch announcement and more at whether ordinary people keep using it month after month.
What to Watch Next
Jamaica’s digital currency story is still being written. The questions that matter now are practical ones: whether more merchants accept JAM-DEX, whether wallets become easier to use, and whether people who mainly use cash find a reason to try it. Cash is not disappearing, and JAM-DEX is designed to work alongside banknotes and coins rather than replace them overnight. If adoption keeps growing, Jamaica’s experiment could become a reference point for other small economies weighing the same choice. If it stalls, it will still have shown what a central bank digital currency looks like in a real island economy, with real shops, real customers, and real habits to change.